Trading US Equities from China: Infrastructure, Platform Access & Cross-Market Reads
TL;DR - China-based traders don't need a simplified gateway to US stocks. They need a professional execution stack - DMA, Sterling Trader Pro, multi-vendor HTB access, real-time order flow, multi-clearing. The Beijing-time advantage (US open lands at 21:30) is structural, not lucky. Whether it converts to P&L depends on whether the trader's order path can compete with the institutional flow that's been waiting for the bell.
This post overlaps deliberately with our deeper US 日内交易基础设施 piece (Simplified Chinese). This English version is the hub for English-readers based in or working with the China market. The Chinese-language piece carries the timing data (SPY 4.8 bp/min at 22:30 Beijing vs 2.3 bp at 03:30) and the local routine. This piece covers the broader execution question.
What Chinese traders actually need beyond the chart
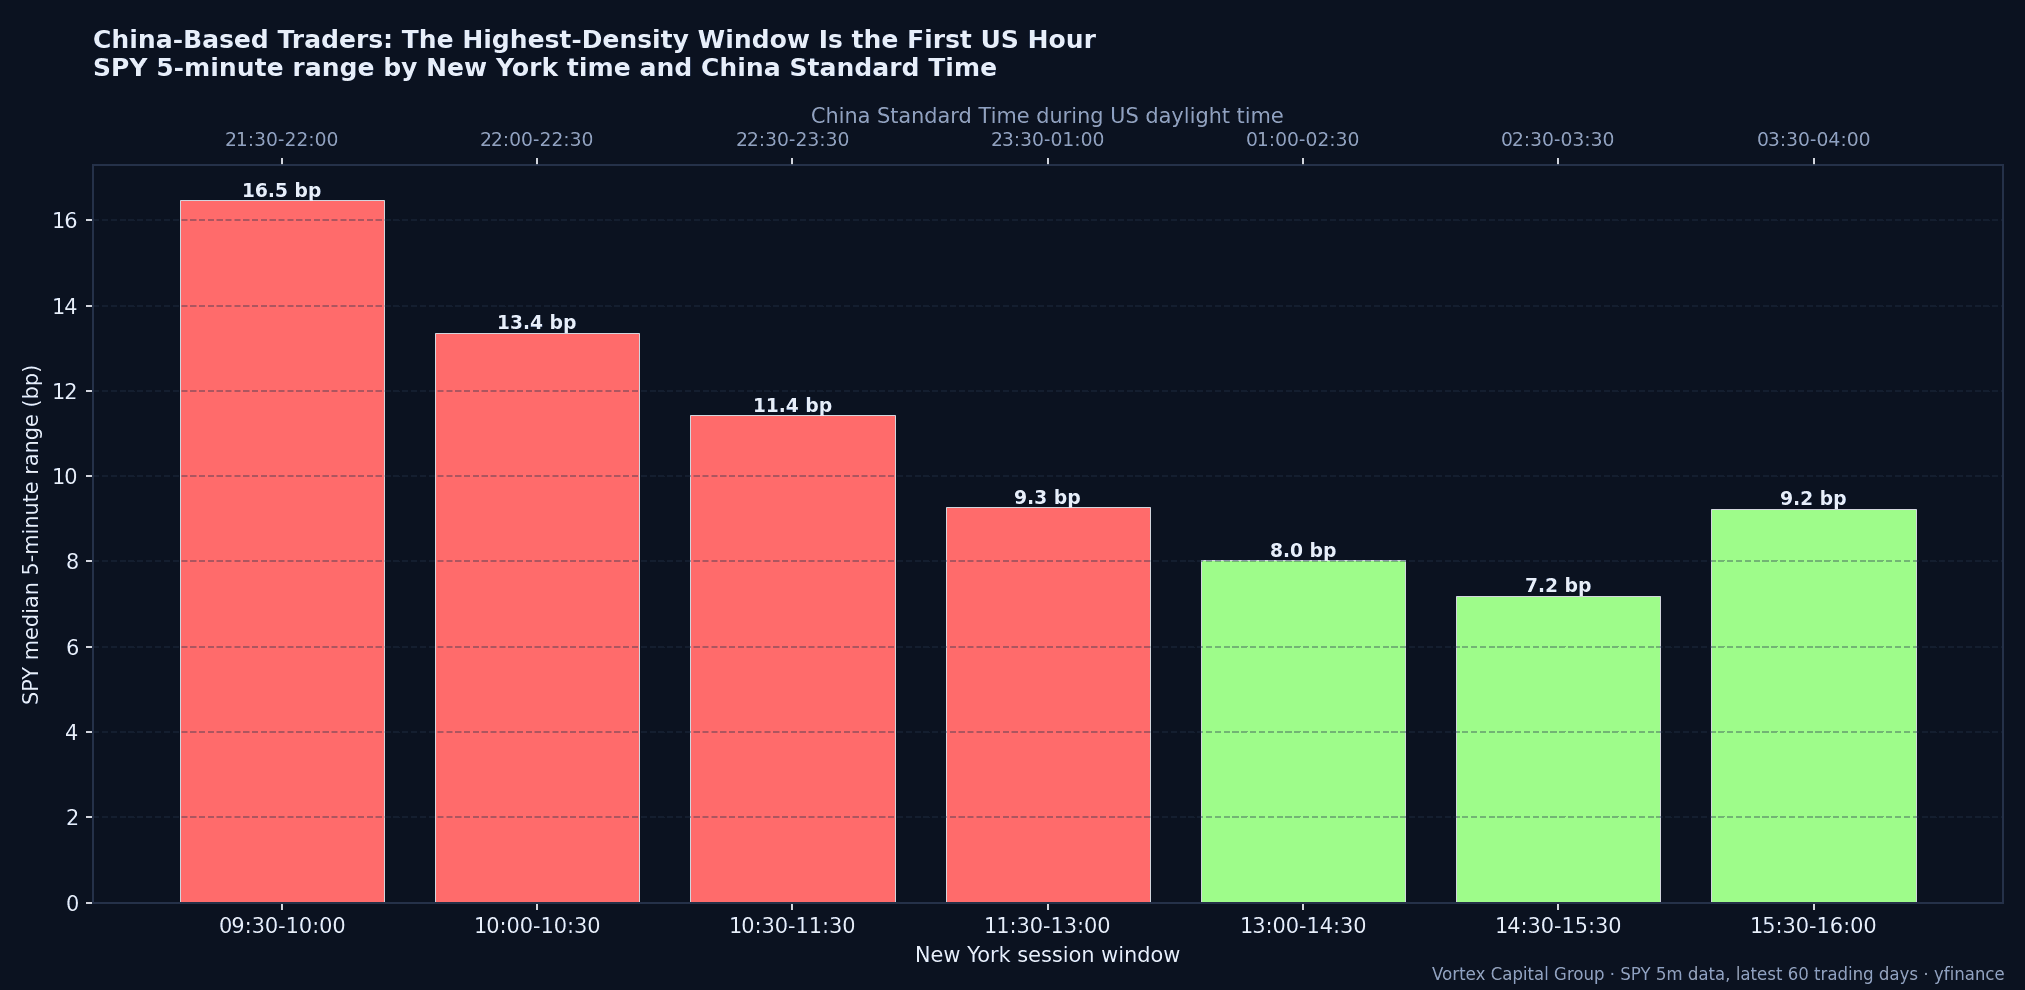
- DMA, not retail routing. Our DMA vs Retail Broker piece shows where retail routing surrenders the most edge during the day's high-volatility windows.
- Multi-vendor HTB access. China ADRs like BABA, JD, PDD often see borrow stress during news/earnings windows. Four HTB Vendors covers why a single vendor is a single point of failure.
- Real-time order flow. CVD, VWAP, heatmap, price ladder - these tools are how the desk separates participation from sponsorship. Our Volume Shock study demonstrates the difference.
- China ADR cross-session reads. The CSI 300 → US-open 6-hour window quantifies how A-share momentum REVERSES in the US session - counter to the textbook reading.
- Multi-clearing redundancy. Borrow, margin, and route choice all improve with more than one clearing relationship - see Multi-Clearing Access.
The cross-market reads that matter
China-based traders have one of the cleanest informational positions in global equities: A-share session, HK session, then US session in sequence. The China ADR Playbook covers BABA / NIO / JD / PDD / KWEB cross-market behaviour. The Hong Kong dual-listing study covers the β < 1 makers' under-reaction. The CSI 300 → US window piece covers how A-share momentum actually inverts intraday in the US.
These aren't theoretical. They're the cross-session reads our desk runs every evening - and they only convert to P&L if the execution stack can act on them at 21:30 Beijing without burning the edge to spread.
Joining the desk
If you're a China-based active trader and you already think in cross-session terms - A-share to HK to US - our trader application takes about ten minutes.
#ChineseTraders #USEquities #DayTrading #DMA #ChinaADR #BABA #JD #PDD #HTBLocates #CrossMarket #PropTrading #VortexCapitalGroup
More for China Traders
- China ADR Trading Playbook: BABA, NIO, JD, PDD & KWEB Flow
- 沪深300到美股开盘的6小时窗口:中概股不是延续A股,而是反转A股Chinese
- 美股日内交易基础设施:中国交易员需要了解什么Chinese
- 暗池交易与机构订单流:主动交易员的结构性优势Chinese
- 美股暗池数据怎么读:TRF 盘外成交与 FINRA ATS 报告的区别Chinese
- 离岸人民币(USD/CNH)隔夜走弱与中概股开盘跳空:7个真实案例的诚实解读Chinese
- 一半的风险发生在美股收盘后:中概股隔夜与日内的方差分解Chinese
- 中概股跳空回补概率:醒来看到跳空,该不该反手Chinese
- 你买的是中国,还是这家公司:单只中概股与 KWEB 的风险分解Chinese
Trade with the desk behind the research
Vortex Capital Group gives qualified traders DMA via Sterling Trader Pro, multi-vendor HTB locates, smart and dark-pool routing, and an 80%+ monthly profit share.
Apply to Trade